The write-offs most tradespeople miss aren't exotic loopholes. They're ordinary expenses claimed at the wrong rate, in the wrong year, or not at all — usually because nobody ever told the owner the rule existed.
Here are the ones that come up most often in trades files around the Tri-Region.
1. Your Truck Might Not Be Subject to the Vehicle Cap at All
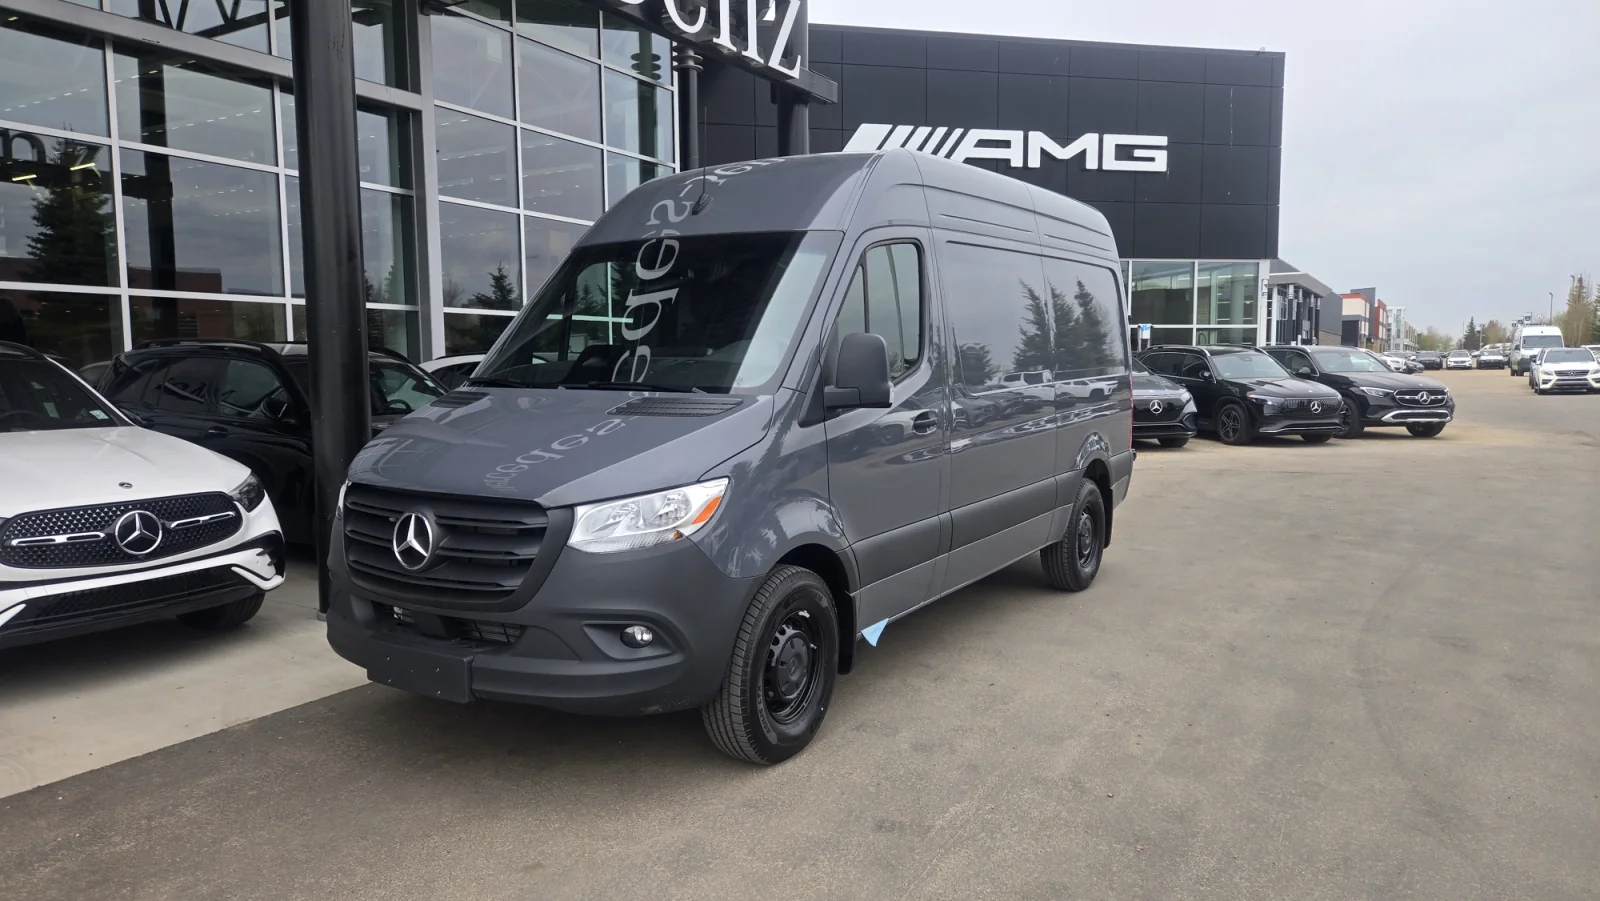
Most owners have heard that CRA caps what you can write off on a vehicle. What far fewer know is that the cap applies to passenger vehicles — and a proper work truck often isn't one.
A van, pickup or similar vehicle can fall outside the passenger vehicle rules based on two things: how many people it seats, and what share of its use is hauling goods and equipment rather than people. Clear those tests and the ceiling on your capital cost disappears. Fall inside the definition and you're capped, no matter what you paid.
What to do: Before you buy, check the cab configuration and be honest about use. A crew cab that seats five and mostly hauls you to quotes is a passenger vehicle. A regular or extended cab hauling material usually isn't. On a well-equipped truck, that distinction is worth thousands of dollars of deduction — so confirm which side you land on before you sign, not after.
2. If the Truck Is in Your Name, Your Corporation Can Pay You Per Kilometre
Incorporated owners often assume the vehicle has to be in the company's name. It doesn't — and sometimes it shouldn't be.
Where you personally own the truck and use it for company work, the corporation can pay you a reasonable per-kilometre allowance. The allowance is deductible to the corporation and tax-free to you. No standby charge, no operating benefit on your T4, no arguing about personal use.
CRA publishes the per-kilometre rate it considers reasonable, and updates it most years. Pay above it and the allowance can become taxable in your hands.
What to do: Run the numbers both ways before the next vehicle purchase. High business kilometres in a personally owned truck often beats corporate ownership once the taxable benefits are counted — but it only works with a mileage log, and the allowance has to actually be paid.
3. First-Year Write-offs on Equipment Have Changed More Than Once
If you're relying on what you learned about writing off equipment a few years ago, that knowledge has probably expired.
The rules governing how much of an asset's cost you can deduct in the first year have been introduced, phased out, and reinstated repeatedly over the past several years. Some generous measures have ended. Others have come back. A few apply only to specific asset classes or to property put into service within a particular window.
The result is that a lot of advice circulating in the trades — including from people who were right when they said it — is now wrong.
What to do: If you're weighing a compressor, a skid steer, a trailer or a shop upgrade, ask what the first-year treatment is for that purchase, in that fiscal year, before you commit. Note that it's usually the date the asset is available for use, not the date you paid, that determines the year you claim it. Timing a purchase around a fiscal year-end can be worth real money — or nothing at all, depending on the rule in force.
4. Small Tools Are Immediate; Big Tools Are Not
Some tools are fully deductible in the year you buy them. Whether a tool is immediately expensed or capitalized over several years often depends on the price of the tool and the useful life of the tool.
The mistake goes both directions. Owners expense an expensive tool that should have been capitalized, or capitalize a truckload of hand tools that could have been written off immediately. The second is the more expensive error, because it quietly defers your deduction for years while you assume you already claimed it.
What to do: Have tool purchases coded properly as they're entered, not sorted out at year-end. Keep the receipts — this is a category auditors sample, and above a modest amount you need the supplier's GST number on the invoice to keep the input tax credit as well.
5. The Shop in Your Garage Counts
If you run the business from home — quoting, invoicing, storing material, parking the truck — a proportional share of your home costs is deductible based on the share of the space used for business.
Alberta winters make the utilities portion meaningful. A heated garage doing double duty as a shop is a real business expense, and plenty of owners never claim a dollar of it.
What to do: Measure the actual space and apply a consistent percentage every year. Don't claim depreciation on the home itself without talking to your accountant first — it can complicate the principal residence exemption when you sell.
6. Wages for Family Members Who Work in the Business
Paying a spouse or an adult child who genuinely does the books, answers the phone, runs parts or handles scheduling is deductible at a reasonable rate for the work performed. It can also create RRSP room and CPP contributions for them.
The word doing the work here is reasonable. The wage has to match what you'd pay an arm's-length person for the same job, and the work has to actually happen.
What to do: Pay it through payroll with proper source deductions and a T4, not as an untracked e-transfer. Keep a short record of duties and hours. This is a well-trodden, entirely legitimate strategy that only fails when there's no evidence behind it.
7. If You Also Hold a T4 Job, Two More Deductions Exist
Plenty of Alberta tradespeople run a side business while still working for someone else. Two employee-side deductions get missed constantly:
•The tradesperson's tools deduction — for eligible tools you were required to buy as a condition of employment. It only kicks in once your tool spending clears an annual threshold, so a light year yields nothing. Your employer has to sign a T2200 certifying the tools were required.
•The Labour Mobility Deduction — for temporary relocation expenses in construction: travel, meals and lodging when a job takes you away from home.
What to do: Ask your employer for the T2200 in January, not in April. Without it, the tools deduction is gone regardless of what you spent.
8. Don't Forget the GST Side of Everything Above
Every deductible purchase above also carries an input tax credit. Materials, tools, fuel, subcontractors, equipment, phone, software, and the business portion of home utilities all have GST you can recover — but only with documentation that meets CRA's requirements, which get stricter as the purchase gets larger.
What to do: Treat your ITC claims as a second pass over the same receipts, not an afterthought. A year of unclaimed credits on materials alone is real money.
Where a CPA Fits
Notice how many of the items above end the same way: ask before you commit. That's not a dodge. Most of these decisions are cheap to get right in advance and expensive or impossible to fix afterward, and the specific numbers attached to each one move every year.
MaryLee Vaughan Professional Corporation is a Chartered Professional Accountant practice in Spruce Grove, serving the area for more than 25 years and working with Alberta small businesses and trades companies — corporate and personal tax, year-end financial statements, tax planning, and CRA notices, reviews and appeals.
If you've got a truck or equipment purchase coming, or you suspect last year's return left money on the table, book a free 20-minute consultation. No pressure and no jargon.
This article is general information, not tax advice. It describes how these rules work rather than the specific dollar limits, which change from year to year. Eligibility depends on your circumstances — confirm the current figures and the details for your situation with your accountant before acting.